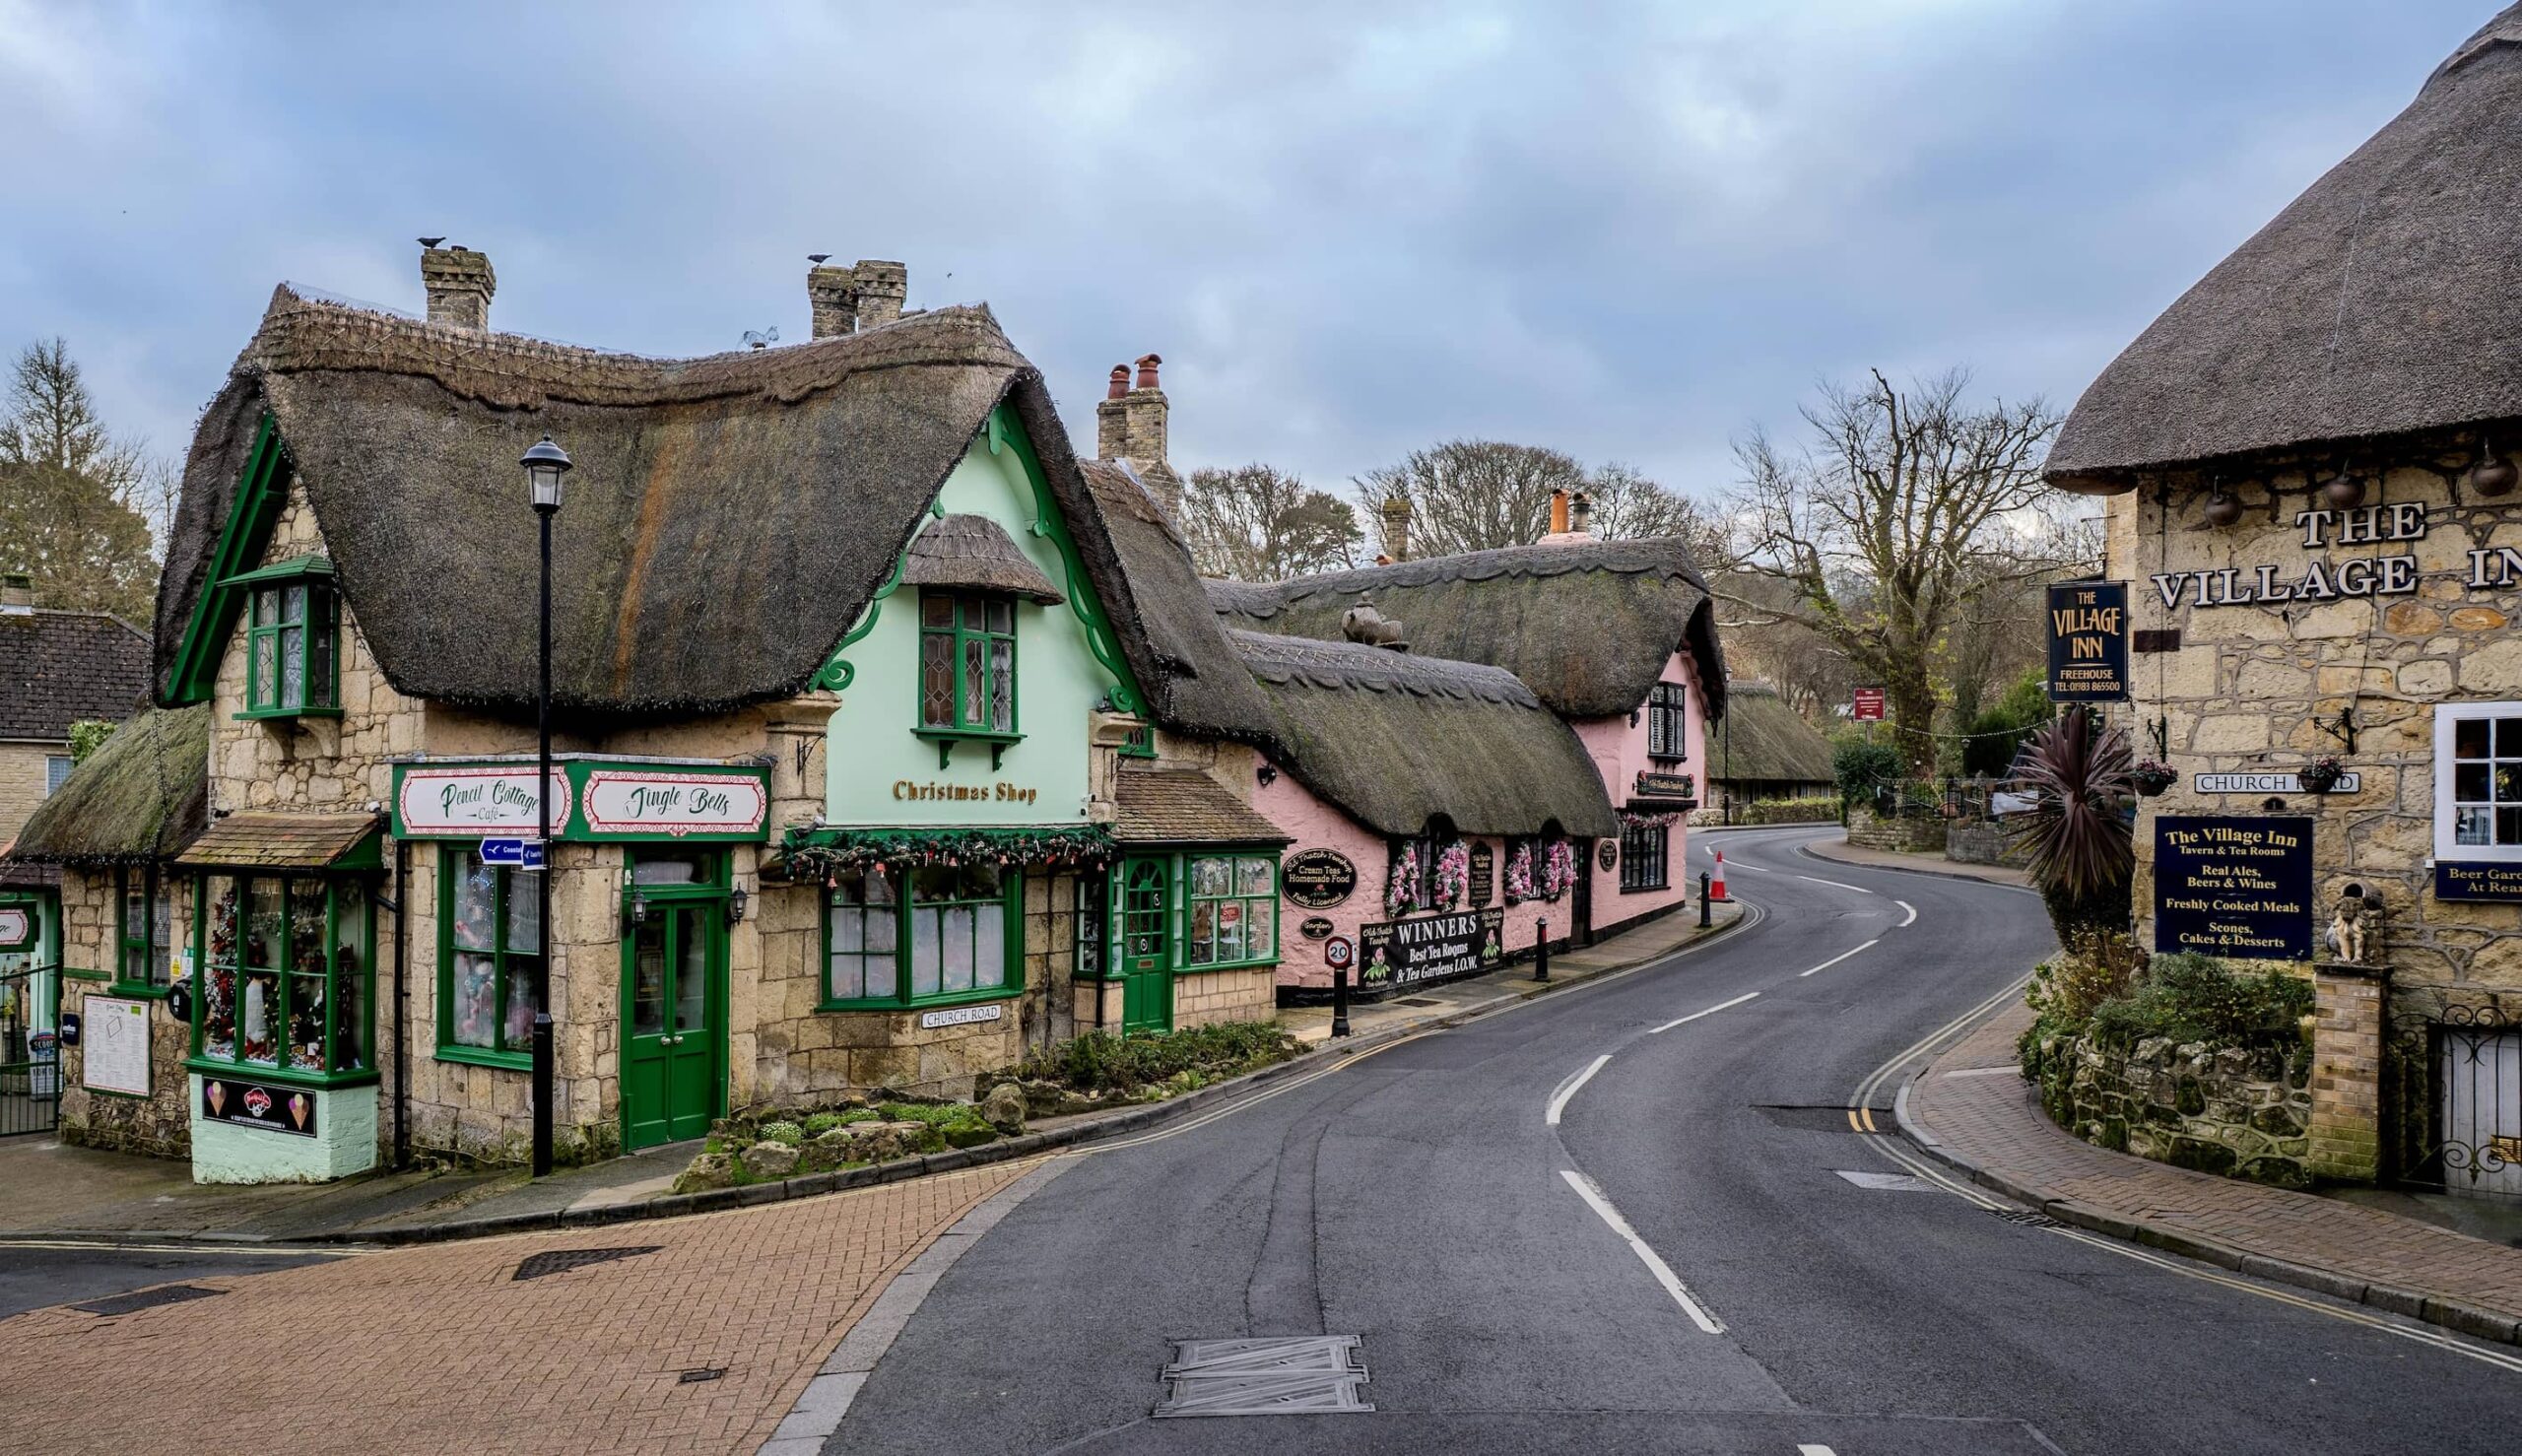
Thatched cottages and Grade II listed homes are some of the most distinctive and historically important properties in the UK. However, many owners are now finding that arranging suitable insurance has become more difficult, more expensive, and more complex than it was even a few years ago.
At Activate Insurance Brokers, we specialise in helping owners of thatched and heritage properties arrange appropriate insurance. We are seeing clear changes in the market, with fewer insurers willing to offer cover and significantly greater scrutiny of rebuild costs and property condition. Understanding what is driving these changes and what you can do about it can help ensure your home remains properly protected.
Rising Rebuild Costs Are Increasing Premiums
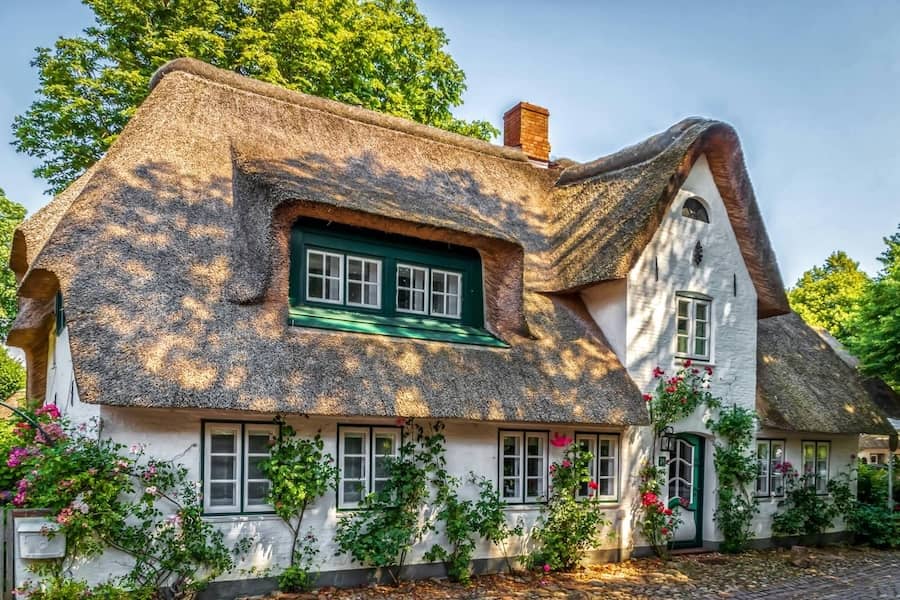
The most significant factor affecting thatched cottage insurance is the cost of rebuilding these properties. Unlike modern homes, thatched cottages must be repaired or rebuilt using traditional materials and specialist craftsmen. This often includes water reed or long straw thatching, traditional timber framing, lime-based plasters, and heritage-appropriate construction techniques.
These specialist skills are in limited supply, and costs have increased considerably in recent years due to inflation, labour shortages, and increased demand. In addition, listed building status can require conservation approval and specialist professional involvement, which further increases rebuild costs.
As insurers reassess these costs, many homeowners are seeing their declared rebuild value increase. Because the rebuild value directly affects the insurance premium, this often leads to higher renewal costs — even where no claims have been made.
At Activate Insurance Brokers, we regularly help clients review their rebuild values to ensure they accurately reflect the property without being unnecessarily inflated. This can help ensure the property is properly protected while avoiding avoidable premium increases.
Fewer Insurers Are Willing to Cover Thatched Properties
Another major change in recent years is the reduction in the number of insurers willing to cover thatched homes. Many mainstream insurers focus on standard construction properties and may not have the underwriting expertise or risk appetite required for heritage buildings.
As a result, homeowners may find that comparison websites produce few suitable quotations, or that premiums increase significantly at renewal when insurers review their portfolios.
Thatched properties require specialist consideration because of their traditional construction, the cost of repairs, and the need to use heritage-appropriate materials. Insurers must also consider the longer time required to complete repairs and the availability of specialist contractors.
Activate Insurance Brokers works with insurers who understand thatched and listed properties. This allows us to help clients access appropriate cover options and navigate a market that has become increasingly specialist.
Insurers Are Applying More Detailed Requirements
Insurers are also asking more detailed questions than in the past. This reflects their need to fully understand the condition, maintenance, and risk profile of each property.
Particular attention is often given to chimneys, fireplaces, and heating systems, as these can present fire risks if not properly maintained. Insurers may expect evidence that chimneys are regularly swept and properly maintained, and they may ask about the installation and servicing of wood-burning stoves.
Roof age and condition are also important considerations. A thatched roof has a long lifespan when properly maintained, but insurers will often want to know when it was last replaced or inspected. This helps them assess the likelihood of repair or replacement in the future.
If a property is unoccupied for extended periods, insurers may also apply specific conditions. This is particularly relevant for second homes or holiday cottages, where regular occupancy cannot always be guaranteed.
We help clients understand these requirements and present accurate information to insurers, which can support more appropriate underwriting decisions.
Claims Can Be More Complex Than Standard Homes
Repairing a thatched or listed property after damage is rarely straightforward. Conservation requirements may apply, and repairs often need to be carried out using traditional materials and specialist contractors. This can extend repair times and increase costs compared to modern properties.
Ensuring that your insurance policy reflects the true nature of your property can help avoid complications in the event of a claim. Policies designed for standard homes may not always reflect the specific requirements of heritage buildings.
Many Homeowners May Not Have Reviewed Their Cover Recently
We often speak to homeowners who arranged insurance many years ago and have renewed automatically since then. However, rebuild costs, insurer appetite, and underwriting requirements have changed significantly.
If your premium has increased unexpectedly, if your roof has been repaired or replaced, or if you have carried out alterations to the property, it may be appropriate to review your insurance arrangements. Regular reviews can help ensure your insurance remains suitable and continues to reflect your property accurately.
How Activate Insurance Brokers Supports Thatched Property Owners
Activate Insurance Brokers specialises in arranging insurance for thatched and listed properties throughout the UK. We understand the unique challenges these homes present and work with insurers experienced in heritage risks.
We assist clients by reviewing existing cover, helping ensure rebuild values are appropriate, and identifying insurers who understand traditional construction. Our role is to help homeowners make informed decisions about their insurance arrangements and ensure they understand the terms and conditions of their cover.
To help reduce the risk of underinsurance, we can arrange specialist rebuild cost assessments through providers such as RebuildCostASSESSMENT. These can be completed as a desktop survey using detailed property data, or where appropriate, a site visit can be arranged to provide a more comprehensive evaluation of the true rebuild cost.
Request a Review of Your Thatched Property Insurance
If you own a thatched property and would like to review your current insurance arrangements or start with a friendly chat, we’re more than happy to help.
Activate Insurance Brokers is authorised and regulated by the Financial Conduct Authority under FRN 1022752. This article is provided for general information purposes only and does not constitute personal advice or a recommendation. Insurance is subject to underwriting criteria, policy terms, conditions, and exclusions, and may not be suitable for all circumstances.